November 11, 2026/
FRED II is a Python-based research framework I developed to explore how trading strategies behave across different economic environments. The...
The Earnings Event Engine is a Python-based research framework I developed to analyze how stocks and options behave around corporate earnings announcements.
The system combines announcement timing, options-implied expectations, realized stock-price reactions, and post-earnings price behavior into a reproducible research workflow.
Key capabilities include:
The demonstration uses deterministic Apple and Microsoft examples to show the actual research pipeline.
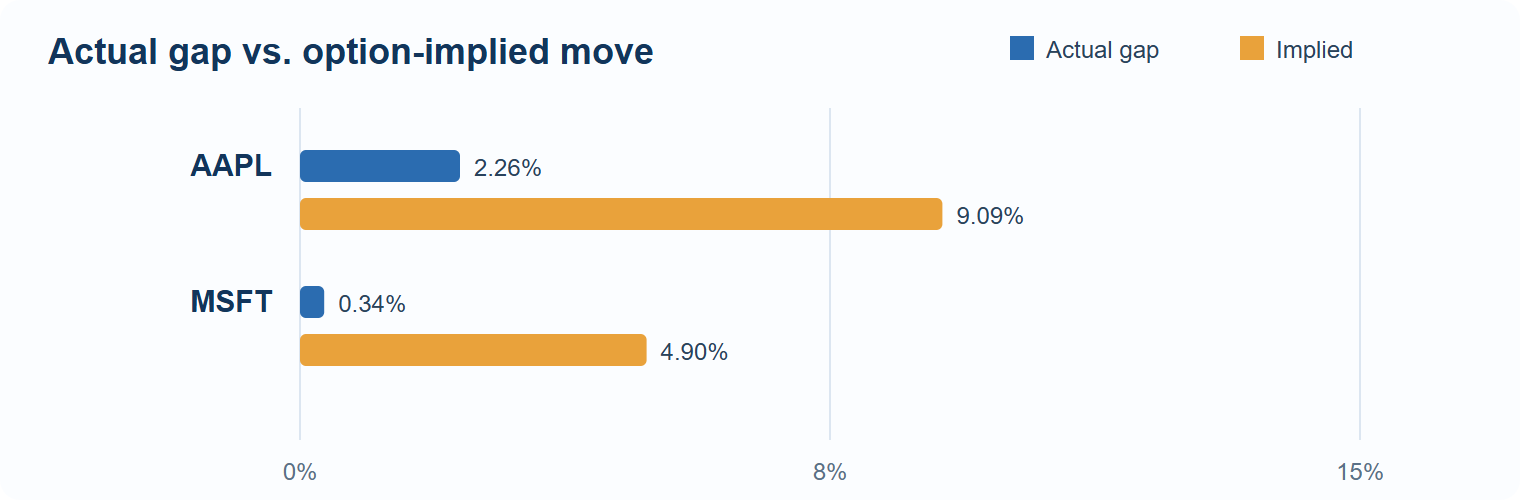
Importantly, the framework does not turn limited observations into unsupported trading signals. It preserves uncertainty and identifies when the available evidence is insufficient for a defensible conclusion.
GitHub: https://github.com/rossautomatedsolutions/earnings_event_engine
Research and demonstration purposes only. Not investment advice.