November 11, 2026/
The Earnings Event Engine is a Python-based research framework I developed to analyze how stocks and options behave around corporate...
FRED II is a Python-based research framework I developed to explore how trading strategies behave across different economic environments.
The project combines historical macroeconomic regimes with strategy returns to examine performance patterns and behavior around changes in economic conditions.
Using 420 months of macroeconomic data from 1991–2025, the framework provides:
For this demonstration, I use real macroeconomic data alongside synthetic strategy returns to showcase the research workflow without representing the examples as actual trading performance.
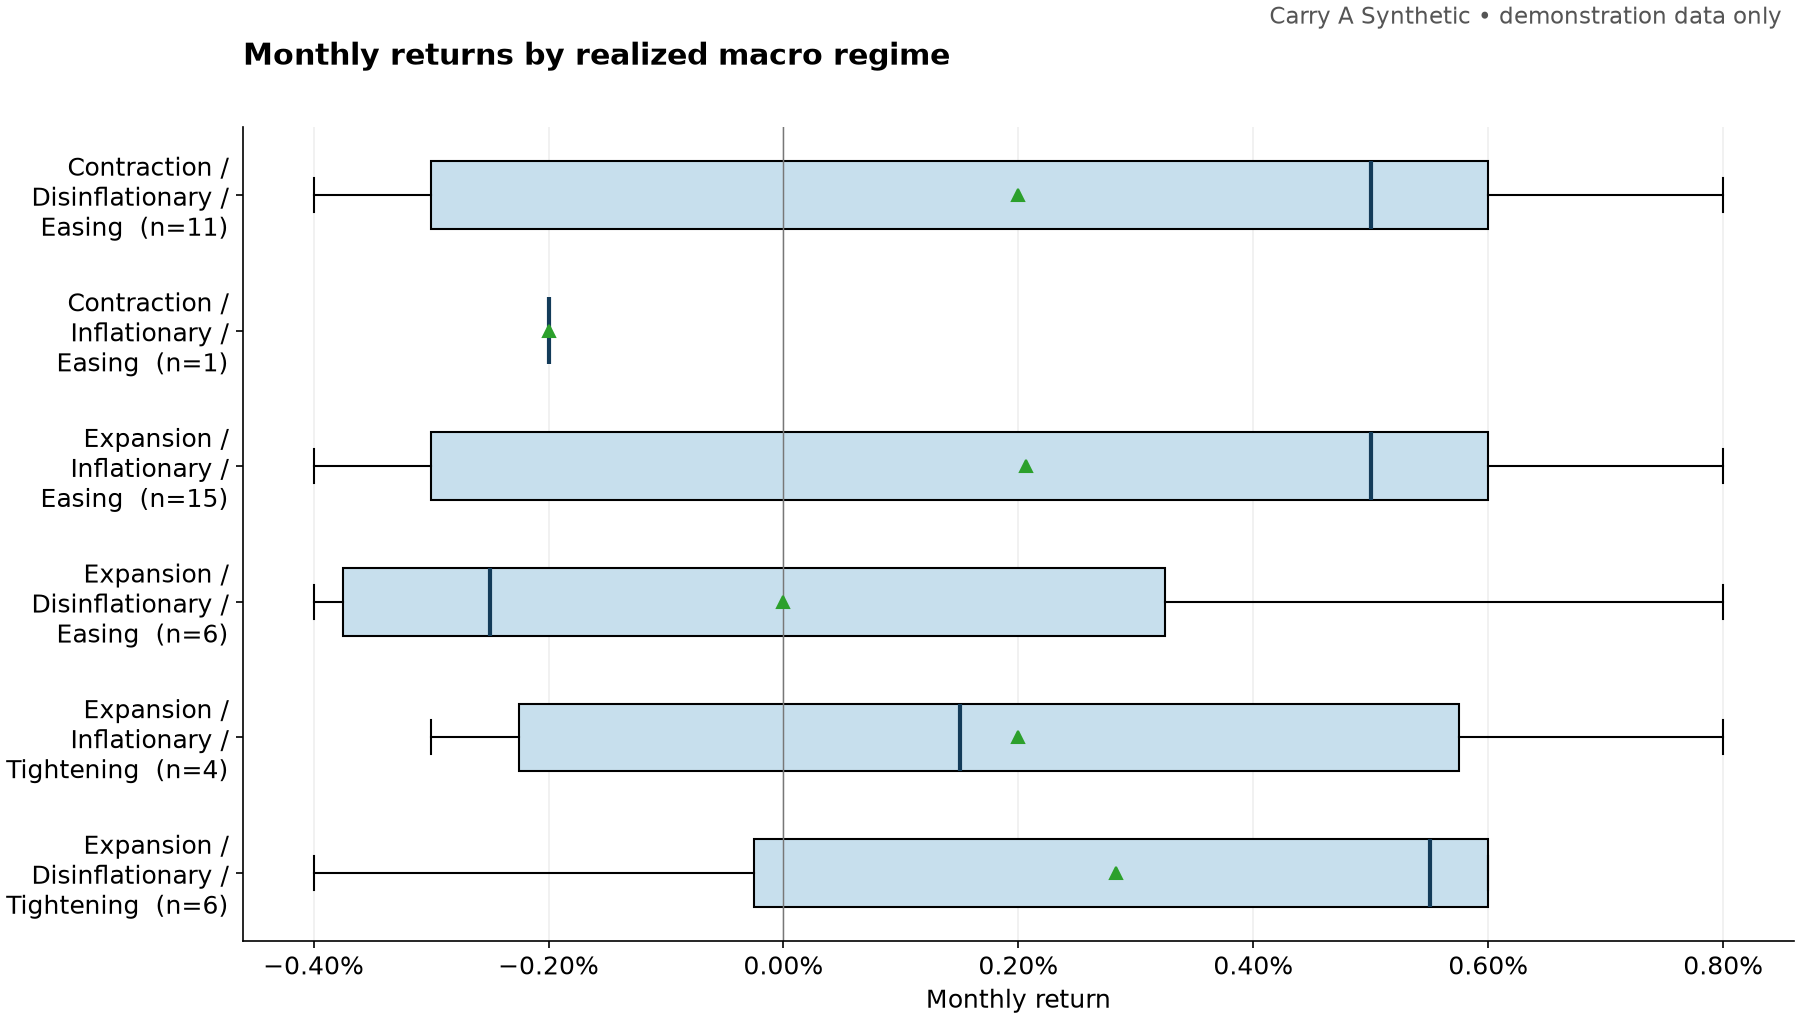
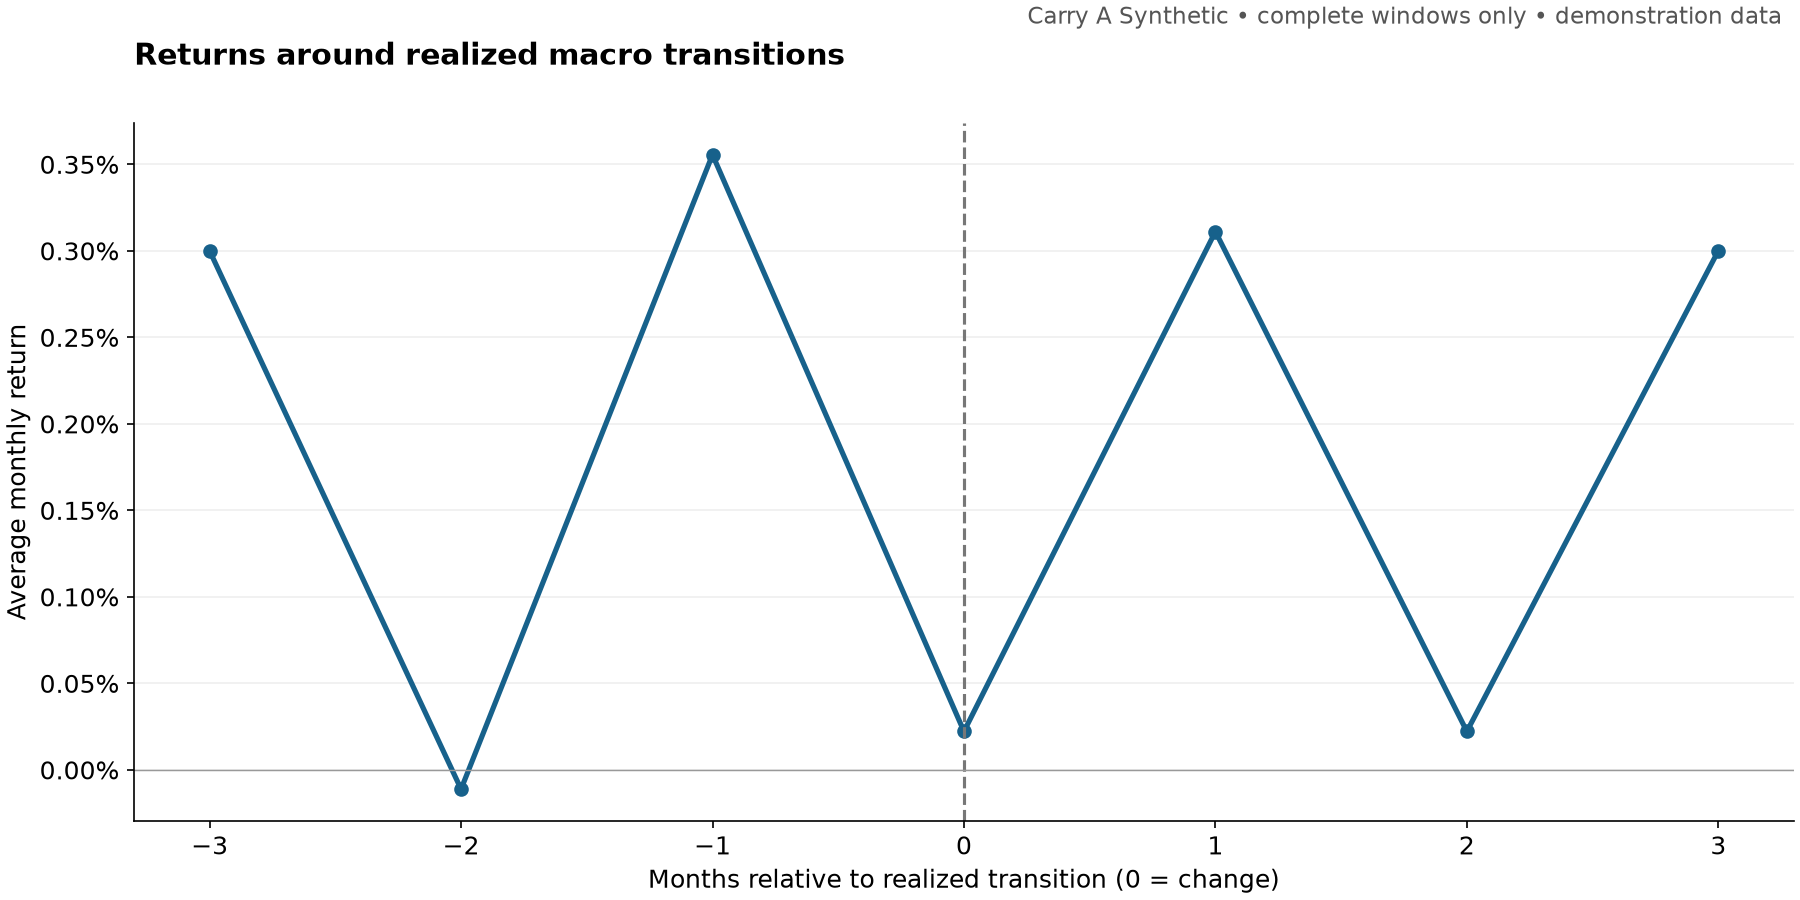
The goal isn’t to predict markets or generate trading signals. It’s to provide a structured way to understand historical strategy behavior within its economic context.
Research and demonstration purposes only. Not investment advice.